Web Design for Insurance Brokers in Ajax
Most industry pages on this site start with what a customer wants. This one starts with a number on a screen, because in Ontario that is the moment a brokerage website stops being marketing and becomes a regulated transaction. Registered Insurance Brokers of Ontario defines a quote as a recommendation that includes price, and five disclosures have to be in front of the reader by then. I have not built a site for a brokerage — the two closest builds, a Richmond Hill law firm and a public adjusting firm in the United States, are described further down.
Everything on the left has to be on the screen before the number on the right appears.
- 01Duty of care — a copy or a link to the CISRO Principles of Conduct and the Fact Sheet About Your Registered Insurance Broker
- 02Compensation and commissions the broker and the brokerage are entitled to, contingent profit commissions included
- 03Third-party financial interest — and there is no minimum material threshold for it
- 04Sales incentives received for selling the policy
- 05Anything else pertinent: an exclusive market, a network affiliation, premium financing, a referral fee
“Recommendation of one or more policies/coverages that includes price.”
RIBO Guidance RIBO-002, Key Definitions
Past this line there is one obligation left, not five: at binding, a written summary of the disclosures already given. The price is an illustration, not a rate.
Sources on this page are primary: the Registered Insurance Brokers Act regulation and the Act itself on e‑Laws, RIBO’s published guidance documents, and Statistics Canada’s business counts. Every Ajax and Durham figure here is recomputed from the raw extract by _ib-data.js.
What does Ontario let an insurance broker’s website say?
Less than most trades, and the limits are written down. Regulation 991 under the Registered Insurance Brokers Act lists twelve kinds of misconduct, and six of them describe things a website does: how it advertises, what name it carries, what it offers, how it compares policies, who it pays for referrals, and whether it lets a reader think a broker is an agent.
That is unusual. On most of the industry pages I write, the law sits somewhere near the work and the website is free to say whatever is true. Here the regulator has published a document with a heading that says WEBSITES, and the sentence under it settles an argument I have had with clients in the first week of a brand-led project. So a brokerage build starts from the list of things the site is not allowed to do, because almost every one of them is a tactic that works fine in the next trade over.
There is a second reason the site carries more weight here than it does elsewhere. RIBO runs two public registers, and I checked what they can actually answer. The broker search takes a first name, a last name or a licence number. The brokerage search takes a brokerage name or a brokerage licence number. Neither has a field for a city. The register is built to confirm a name you already have, and it says so: it “does not provide full licensing history or details about any conditions or restrictions associated with the license.” Nobody in Ajax can start at RIBO and work outwards to a broker near them. They start on Google, and they land on a website.
This page is the Ajax half of a pair. The wider version, with the guidance ladder and the rules that apply anywhere in the province, is on the pillar: web design for insurance brokers and brokerages.
When does a brokerage website become a “quote”?
When a price appears next to a recommendation. RIBO’s Mandatory Disclosures guidance defines a quote as a “recommendation of one or more policies/coverages that includes price” and defines point of sale separately as binding the contract. Disclosure is owed at the first of those, not the second — so the number is the deadline.
Two sentences in that guidance decide how the disclosure is built rather than whether it exists. The first: written confirmation “must also be specifically drawn to the client’s attention. This includes using visual cues or verbal instructions on accessing the disclosure documents.” The second: RIBO “will consider that a broker has not complied with these disclosure requirements if it is provided in a manner that is unclear or vague. For example, if the disclosure is buried in a package of voluminous documents and can be easily overlooked or missed by the client.”
Read together, those rule out two convenient placements. A link in the footer is not a visual cue. A twelve-page PDF attached to the quote email is a voluminous package. What satisfies both is a short, named, visible block that sits beside the number, with the two documents reachable in one click and the brokerage’s own statements written out rather than referenced. That is a component, and it belongs in the template once rather than on each page by hand.
| Disclosure | What RIBO-002 requires | Where it lives on the site |
|---|---|---|
| Duty of care | A copy or a link to the CISRO Principles of Conduct for Insurance Intermediaries and the Fact Sheet About Your Registered Insurance Broker. | Two permanent URLs, linked from the disclosure block and from the quote confirmation email, never only as attachments. |
| Compensation and commissions | The forms of compensation the broker and the brokerage are entitled to, contingent profit commissions included, with the brokerage’s statement of compensation. | A page of its own, written in plain sentences, linked by name rather than as “learn more”. |
| Third-party financial interest | Whether an insurer, an affiliate or a holding company has a financial interest. “There is no minimum material threshold for this disclosure.” | One paragraph on the same page, kept current — RIBO’s own renewal data puts 20% of firms in this position. |
| Sales incentives | Whether the broker receives incentives for selling the policy, monetary or not, including travel, goods and hospitality. | Same page, same block. It is the shortest of the five and the easiest to leave out when the page is written once and never revisited. |
| Anything else pertinent | An exclusive arrangement with a single insurer, a network affiliation, premium financing, an unlicensed insurer, a referral fee being paid or received. | Conditional lines in the disclosure component, switched on per line of business rather than rewritten. |
The guidance adds one line that reaches past the page and into the software: “Any automated quoting software should include a process to provide mandatory disclosures at the point of quote. These disclosures must be drawn to the customer’s attention before the contract and other documents are sent for signature.” If a quoting widget is embedded in the site, that sentence is a specification for the widget, and it is the brokerage’s obligation rather than the vendor’s.
Can a brokerage run a review campaign on its website?
It can ask for reviews. It cannot sort them. On 1 June 2026 RIBO published Guidance RIBO-006 on online conduct, and it names review gating — routing happy customers to a public review and unhappy ones to a private form — as a false and misleading form of advertising, prohibited as misconduct by section 15 (1) paragraph 1 of Regulation 991.
This matters more to a web designer than to a broker, because the gate is something a designer installs. It arrives as a plugin, a reputation widget or a line in a marketing retainer. The guidance closes that door by name: review manipulation “includes actions taken by the licensee, by employees, by contractors, or by third‑party marketing agencies acting on the licensee’s behalf.” An agency cannot hold the tool at arm’s length on the client’s behalf.
“How would you rate your experience?”
Sent straight to the public review page, with the link pre-filled.
Diverted to a private customer-service form that nobody else will ever read.
RIBO’s wording covers both arms at once: “marketing campaigns or automated systems that encourage satisfied consumers to leave public reviews while redirecting dissatisfied consumers to private customer‑service channels, that can cause a misleading impression of the firm.”
- Asking consumers to leave a review — plainly, without conditioning the ask on how they feel.
- Reporting a fake or malicious review to the platform, including a false or misleading Google review.
- Suppressing reviews that are fake, malicious or otherwise offensive.
Three more items on RIBO’s prohibited list are things a website can do on its own: editing or rewriting a consumer review before displaying it, using fabricated or inauthentic testimonials in promotional material — the guidance names AI‑generated testimonials specifically — and incentivising a review that would not reflect a genuine experience, or failing to disclose that an incentive was given. The second of those is why I render reviews from the platform they were left on rather than retyping them into the page: a quote that cannot be traced back to a source cannot be shown to be authentic either.
What can an insurance brokerage actually offer online?
Nothing that is contingent on buying a policy. Section 15 (1) paragraph 3 of Regulation 991 makes it misconduct to offer money or a thing of value as an inducement to insure, and paragraph 4 prohibits rebating any part of the premium. RIBO’s Marketing Guidelines then work through the ordinary marketing catalogue case by case.
The board below is that catalogue, restated as things a client might ask for in a web project. Every verdict on it comes from the Guidelines or from the regulation; nothing on it is my reading of what is probably fine. The Guidelines also say, at the top of the document, that RIBO “strongly recommended that all proposed marketing plans be submitted in writing to RIBO for review, prior to launching any new program” — which is a sentence worth putting in a web-design proposal, not just in a compliance file.
A gift card for requesting a quote
Not permittedA thing of value offered to a prospective insured to induce them to insure. The inducement is what is banned, not the gift card.
Reg. 991, s. 15 (1) 3Branded swag on the contact page
ConditionalGiveaways are acceptable where they are nominal in value — under $100 — and not tied to the purchase of insurance.
Marketing Guidelines, Giveaways“Refer a friend, get $50”
Not permittedReferral fees may only pass between the financial-services categories the regulation lists. Fees to non-financial industry parties are not permitted, and the general public is not on the list.
Reg. 991, s. 15 (1) 12A referral arrangement with a mortgage broker or realtor
ConditionalPermitted with full disclosure and the client’s written consent in advance, and only where the broker gives no advice they are not licensed to give.
Reg. 991, s. 15 (1) 12 · Marketing GuidelinesA spin-to-win or prize draw on the site
ConditionalA raffle or contest is acceptable as long as entry is not tied to buying an insurance product. The moment a policy is the price of entry, it is an inducement.
Marketing Guidelines, Raffles and Contests“We donate $10 per policy to a local charity”
Not permittedA broker may advertise that it supports a charity. Advertising that a share of commission or premium goes to that charity, as a reason to insure, is improper.
Marketing Guidelines, Donations“We’ll beat your renewal or pay the difference”
Not permittedRebating is strictly prohibited: no agreement on premium other than as set out in the policy, and no consideration in the nature of a rebate.
Reg. 991, s. 15 (1) 4A bundle page — insurance plus alarm monitoring, one price
Not permittedJoint advertising with a non-insurance business is fine. Selling the insurance product together with a non-insurance product at one price is not.
Marketing Guidelines, Joint Advertising“Leave us a review and get a coffee card”
Not permittedIncentivising a review that would not reflect a genuine experience is review manipulation, and so is failing to disclose an incentive that was given.
RIBO-006, Review ManipulationOne nuance worth keeping straight, because it looks like a contradiction. The Guidelines accept loyalty points and card rewards offered in conjunction with buying insurance, while treating bonus points plans as possible inducements to be referred for approval. What decides it is whether the thing of value exists in order to make someone insure. A designer cannot settle that from the copy deck, which is exactly why the written-review step above belongs in the plan.
Does the name in the header have to be the registered one?
Yes, and this is the one rule with its own heading in RIBO’s Marketing Guidelines. “Websites must clearly identify the RIBO registered name of the brokerage. Websites cannot advertise or operate under a trade name only, as trade names are not legal entities.” Guidance RIBO-006 repeats it for every advertisement: the legal name, or the legal name and the trade name together.
In practice that is a decision made in the first hour of a project, and it is easy to make without noticing. A brokerage that trades as a short, friendly name will want that name in the logo, the title tag, the footer and the Google Business Profile, and there is no design reason to refuse. Unless someone raises the rule, the registered name ends up on the invoice and nowhere else.
Service in City | Registered Name Inc. — the site name in search results is an advertisement too.“Meet our agents” — paragraph 10 makes it misconduct to advertise in a way that leads a reasonable person to believe a member is an insurance agent. Brokers and agents are different licences, and the word is not interchangeable copy.
A trade-name-only site with the legal entity nowhere on it — the Guidelines settle this one explicitly, in the only paragraph they write about websites at all.
A producer’s personal site launched without sign-off — a website created, owned and operated by a producer of a brokerage must first have the principal broker’s authorization before it launches.
There is a related page the regulation reaches without naming it: the comparison table against “your current insurer”. Paragraph 2 makes an incomplete comparison of a policy with another insurer’s misconduct where it is used to induce someone to lapse or surrender a policy, and paragraph 1 catches advertising that misrepresents benefits by omission. A three-row table is an incomplete comparison by construction. The version that survives both is a page about how to read a policy, with no second column.
Is the embedded quoter the brokerage’s problem or the vendor’s?
The brokerage’s. RIBO’s Take-All-Comers guidance, published on 11 December 2025, says licensees are responsible for compliance across “all of their outsourced activities, contracts, agreements, and any relationships with third parties including aggregators, online quoters, and Broker Management System (BMS) providers.”
That same guidance contains the only performance requirement I have ever seen a regulator write into a conduct rule. Among the things a brokerage must be able to demonstrate during a spot check: that it has “confirmed that automated quoting processes are instantaneous as unjust delays are effectively treated as declining coverage.” Seventy-six per cent of Ontario firms reported selling auto insurance in RIBO’s last renewal questionnaire, so for most brokerages this applies to the busiest form on the site.
A page that takes nine seconds to return a rate is normally a conversion problem that someone gets to next quarter. Here it is closer to a conduct problem, and it moves up the build order accordingly: server-side rendering for the form, a measured time-to-first-quote, and a visible state when a market cannot answer, rather than a spinner that leaves the visitor guessing whether they were turned down.
Two more obligations shape what the site has to store rather than show. Section 230 (1) of the Insurance Act requires a broker to give an applicant “the names of all the insurers with whom the broker has an agency contract relating to automobile insurance and all information obtained by the broker relating to quotations on automobile insurance for the applicant”. And the guidance expects a complete quote log in each consumer file, capturing all available market quotes and the related commentary, retained for a minimum of six years. A quote form that emails a lead notification and keeps nothing is not a record.
Have you built a website for an insurance brokerage?
No, and I would rather say that than dress up an adjacent job as this one. Two builds sit close enough to be worth reading. One is a law firm in Richmond Hill, where a regulator also decides what the site may claim. The other is a public adjusting firm in the United States — the claims side of the same industry, where no page may promise an outcome.
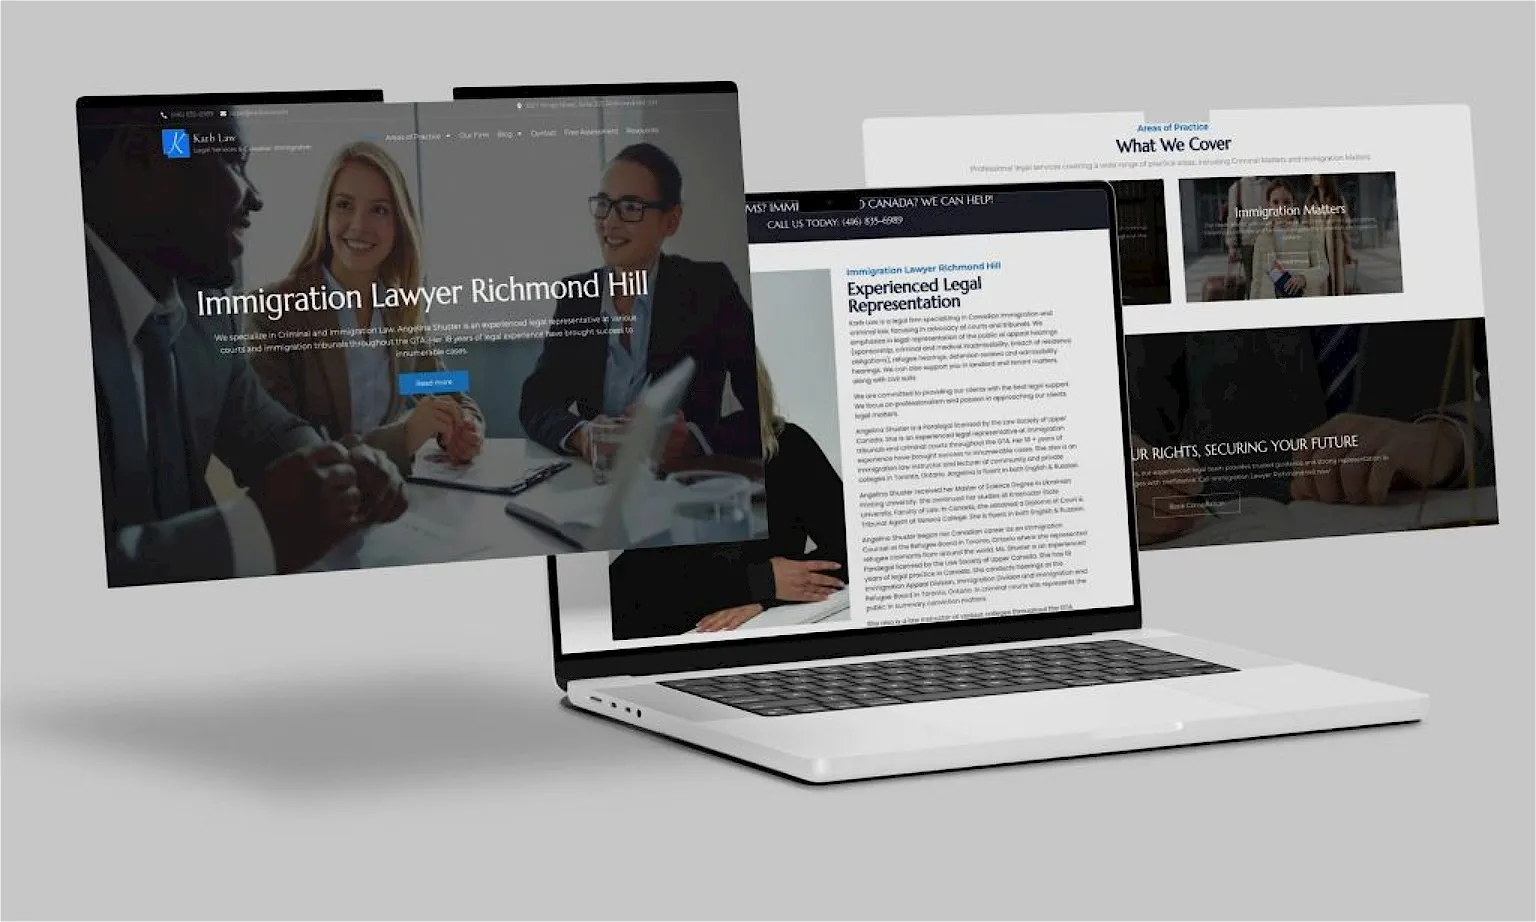
The Richmond Hill legal practice — designed and built here
Karb Law is a legal services firm in Richmond Hill, Ontario. I designed and hand-coded the site: mobile-first, structured for local search, no template and no page builder. What makes it the closest thing I have to a brokerage build is the shape of the problem rather than the trade. A licensed title and a mandatory disclosure sit between the visitor and the first conversation, and the persuasive weight has to come from credentials and a plain description of process, because an outcome cannot be promised.
That build is also the anchor for the other regulated practices I write about — mortgage brokers and agents and accounting firms and CPAs — and an insurance brokerage is the next member of the same family, with a stricter rule set. Read the law firm case study.
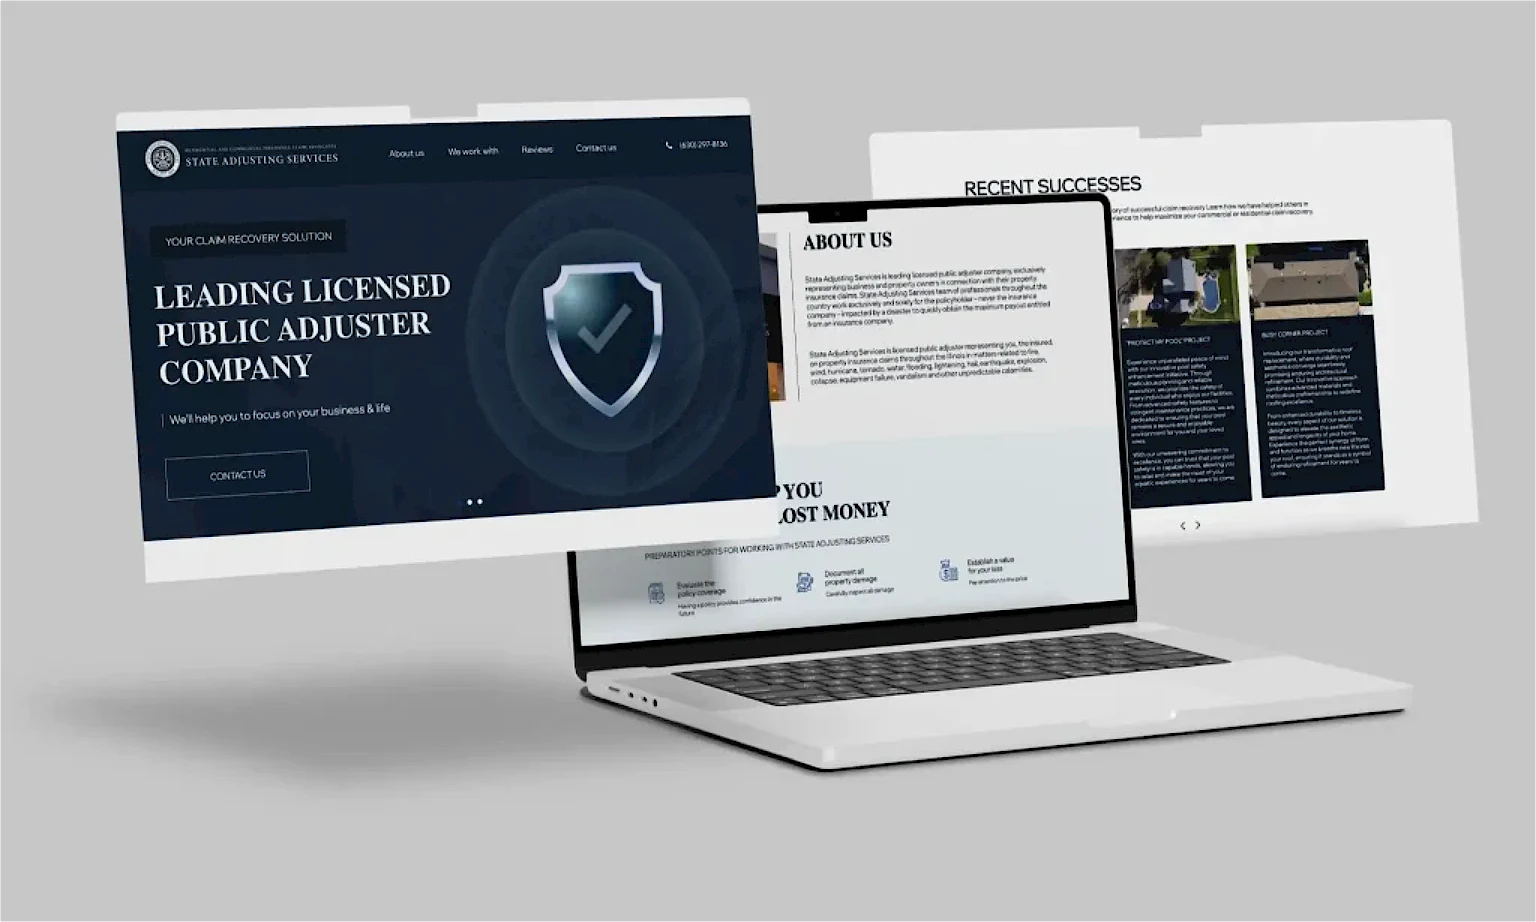
The public adjusting site — the claims side of the same industry
State Adjusting is a public adjusting firm in the United States, and I designed and built the site. Its whole job is to explain a complicated insurance process to someone who did not choose to learn it, and to do that without promising a result. The parts that transfer to a brokerage are the ones that took the longest: a step-by-step explanation that a stressed reader can follow, and restraint in the claims, which is the same constraint Regulation 991 puts on a broker in harder language.
Read the insurance adjuster case study, or the industry page for public adjusters and its city page in Mississauga.
If a brokerage in Ajax wants a page of mine that names a brokerage client, I do not have one. What I do have is the regulated-practice pattern above, the primary sources this page is built from, and the local numbers below for the market a site like this would be selling into. For the wider local picture see web design in Ajax and Ajax SEO, and tell me about the site you have now on the contact page.
How many insurance brokerages are there in Ajax?
Twenty-seven, on the closest official count available. Statistics Canada’s business counts put 27 businesses with employees in Ajax in the insurance agencies, brokerages and other insurance related activities group as of January 2026. Twenty of the 27 have one to four employees. Twenty-six of the 27 have fewer than twenty. None has fifty or more.
That last line is the one that decides how a brokerage website should be built. The largest firm of the 27 employs somewhere between twenty and forty-nine people, and 20 of them employ four or fewer. At that size the disclosure block, the review-request wording and the quoting widget are all owned by the same person, and that person also sells insurance. A build that assumes otherwise — a site that needs a specialist to change a paragraph — is the wrong build, whatever it looks like.
Ajax sits 29th of the 254 Ontario census subdivisions that report any business in this group. Across the province the same table counts 4,024 of them, and 2,173 — 54.0% — have one to four employees, so the shape in Ajax is the shape of the trade rather than a local quirk. Seventy-four Ontario municipalities have exactly one.
| Durham Region municipality | Businesses with employees | Rank in Ontario |
|---|---|---|
| Whitby | 39 | 19 |
| Oshawa | 37 | 22 |
| Pickering | 34 | 26 |
| Ajax | 27 | 29 |
| Clarington | 23 | 35 |
| Uxbridge | 8 | 67 |
| Brock | 6 | 78 |
| Scugog | 6 | 86 |
One hundred and eighty across Durham Region, 160 of them in the five lakeshore municipalities. For a brokerage in Ajax that is the useful reading: the competitor set is regional, not municipal, and a resident comparing three websites will not notice which side of a boundary each one sits on. It is also the argument for writing a page per line of business rather than a page per neighbouring town.
Three limits on these counts, all of them worth stating. The table counts businesses with employees, so an owner-only brokerage with no payroll does not appear — 27 is a floor. The group is NAICS 5242, “agencies, brokerages and other insurance related activities”, which also contains claims adjusters and other insurance-related businesses, so not all 27 are RIBO-licensed brokerages. And a count is by business location on the Business Register, which is not the same thing as where the clients are.
Source: Statistics Canada, Table 33‑10‑1176‑01, Canadian Business Counts, with employees, census metropolitan areas and census subdivisions, June 2026, released 14 August 2026, reference period January 2026; NAICS member “Agencies, brokerages and other insurance related activities [5242]”. Pulled 20 September 2026. RIBO figures are from its 2024–2025 Renewal Report and 2024–2025 Spot Check Report.
What pages does a brokerage website in Ajax need?
Seven, and two of them exist only because of the rules above. The line-of-business pages, the claims page, the about page and the local page are ordinary search work. The disclosure set and the verification route are not, and building both once as components is what keeps the site maintainable by a small office.
| Page | Who arrives | What shapes it |
|---|---|---|
| A page per line of business | Someone with one risk in mind: a car, a house, a truck, a small business. | Ordinary search intent. Seven markets on average means a real choice to describe, not a single product to sell. |
| Disclosures | Anyone about to see a price, and RIBO during a spot check. | RIBO-002: compensation, third-party interest, incentives, the two duty-of-care documents. |
| Quote request | The largest single group, usually on a phone, usually outside business hours. | Disclosure at the time of quote, an instantaneous automated path, and a stored quote log rather than an email. |
| Verify us | The careful buyer, and anyone who has just read a warning about insurance fraud. | The registered name, plus the route to the RIBO brokerage search — the register the visitor cannot reach by geography. |
| Claims | An existing client on the worst day of their policy year. | Not a sales page. Phone first, what to have ready, what happens next. |
| About and people | A local buyer deciding whether this is a real office in Durham. | Named licensed staff, with the word broker used accurately throughout. |
| Ajax and the neighbouring towns | Search traffic from a regional competitor set of about 160 firms. | One honest local page, not eight near-identical ones. The boundary means nothing to the buyer. |
RIBO’s own spot checks are a useful sanity check on where the effort should go. Of the 60 completed in 2024–2025, 75% of brokerages had proper written disclosure record keeping, where the year before 57% did not, while 31% still had no process for tracking continuing education and 11% had no written office procedures at all. Disclosure is the part the industry is actively fixing, which is a reason to build it properly rather than to treat it as settled.
What an insurance brokerage website costs
A build of this scope is $899 to $2,999 one time and goes live in 5 to 7 days once content is ready. Fixed price, agreed in writing before work starts. What moves it inside that range is the number of lines of business with their own page, whether the disclosure set is built as a reusable component, and whether an online quoter is embedded.
$899 covers up to ten pages, which is enough for a brokerage with three or four lines of business, the disclosure set, a claims page and one local page. $1,499 fits a larger structure where each line of business earns its own page and its own quote path. $2,999 is where booking, payments or a portal are involved. I will look at what you have now and tell you honestly whether it needs a rebuild or a repair — on a small brokerage site the answer is often the second one.
See pricing in full, or what a build includes on the web design page. If the site is fine and the problem is that nobody in Ajax finds it, that is SEO and Google Maps setup instead.
Insurance Brokerage Website FAQ — Ajax
When does an insurance brokerage website become a quote?+
The moment it shows a price against a recommendation. RIBO Guidance RIBO-002 defines a quote as a recommendation of one or more policies or coverages that includes price, and requires the mandatory disclosures no later than at the time of quote. A number on the screen is therefore the line, not the signature that follows it.
Can a brokerage send happy clients to Google and unhappy clients to a private form?+
No. RIBO Guidance RIBO-006 names that pattern as review gating and calls it a false and misleading form of advertising, explicitly prohibited as misconduct by section 15 (1) paragraph 1 of Regulation 991. The guidance applies the same rule to third-party marketing agencies acting on the brokerage’s behalf.
Can an insurance brokerage offer a gift card for a quote?+
Not as an inducement to insure. Section 15 (1) paragraph 3 of Regulation 991 makes it misconduct to offer money or a thing of value to induce a prospective insured to insure. RIBO’s Marketing Guidelines allow giveaways that are nominal, under one hundred dollars, and not tied to the purchase of insurance.
Does the website have to show the RIBO registered name?+
Yes. RIBO’s Marketing Guidelines state that websites must clearly identify the RIBO registered name of the brokerage and cannot advertise or operate under a trade name only, because trade names are not legal entities. Guidance RIBO-006 repeats it for every advertisement, online or not.
Is a third-party online quoting tool the brokerage’s compliance problem?+
Yes. RIBO Guidance RIBO-004 states that licensees are responsible for Take-All-Comers compliance across all outsourced activities and relationships with third parties, naming aggregators, online quoters and broker management system providers. The same guidance expects automated quoting to be instantaneous, because unjust delays are effectively treated as declining coverage.
Can a broker use the word agent on the website?+
Not about themselves. Section 15 (1) paragraph 10 of Regulation 991 makes it misconduct to advertise or conduct yourself so as to lead a reasonable person to believe you are an insurance agent, and RIBO-006 repeats that licensees must not represent themselves in a role inconsistent with their licence.
How many insurance brokerages are there in Ajax?+
Statistics Canada counts 27 businesses with employees in Ajax in the insurance agencies, brokerages and other insurance related activities group as of January 2026. Twenty of them have one to four employees, five have five to nine, one has ten to nineteen and one has twenty to forty-nine. None has fifty or more.
Have you built a website for an insurance brokerage?+
Not for a brokerage. The two closest builds are a Richmond Hill law firm, where a regulator also governs what the website may claim, and a public adjusting firm in the United States, which is the claims side of the same industry. Both were designed and hand-coded here.
How much does an insurance brokerage website cost?+
A build of this scope is $899 to $2,999 one time and goes live in 5 to 7 days once content is ready. What moves it within that range is how many lines of business get their own page, whether the disclosure set is built as a reusable component, and whether an online quoter is embedded.
Send me the site you have now, and I will mark it against these rules
Brokerages in Ajax, Pickering, Whitby and across Durham — you get a page map and a plain list of what the rules above already cover back before any quote. Packages from $899.