Insurance Broker Website Design in Ontario
A brokerage website is not governed by one rule. It is governed by a regulation that lists twelve kinds of misconduct, and by a stack of guidance documents the regulator has been rebuilding one section at a time. Two of the nine landed in 2026, one of them specifically about what happens online, and a tenth on referrals has been announced and not yet published. This page is the version of that stack a web designer needs.
Each one interprets the Registered Insurance Brokers Act and Regulation 991. The amber rungs are the ones written in 2026.
Fair Treatment of Customers
Update the client’s needs, educate, document the communication, disclose conflicts and commissions.
Mandatory Disclosures
Five disclosures, owed no later than at the time of quote — and a definition of “quote” that decides when your website has made one.
CISRO Conduct Guidance and Mandatory Fact Sheet
The two documents a client has to be given, which means two permanent URLs on the site.
Licensee Requirements and the Take-All-Comers Rule
Names aggregators, online quoters and broker management systems as the licensee’s responsibility, and expects automated quoting to be instantaneous.
Sole Occupation Requirement
A secondary business needs an exemption granted before any involvement in it — which reaches a producer’s side project and its website.
Online Conduct: Social Media and Review Manipulation
Advertising must carry the registered name; review gating and incentivised reviews are misconduct, including when an agency does it for you.
Referrals — announced, not yet published
Until it arrives, referral arrangements run on the 2016 Marketing Guidelines and paragraph 12 of the regulation.
Guidelines on Marketing Practices
Still in force, still the only document with a heading that reads WEBSITES. Being replaced section by section.
Two more sit alongside these: Guidelines to Assist in Completing Form 1 (2018) and Unlicensed Insurers (2023). RIBO reviews each document within three to five years of publication, and guidance under review stays in force until it is updated or withdrawn.
Compiled from RIBO’s own guidance index and the documents it links, together with the Registered Insurance Brokers Act regulation on e‑Laws. Read 20 September 2026.
What should an insurance brokerage website include?
Seven things. The registered name of the brokerage on every surface, a page for each line of business, a disclosure set, a quote path that shows those disclosures before it shows a price, a claims page written for an existing client rather than a prospect, a people page that uses the word broker accurately, and a visible route to the RIBO register so a visitor can check you.
Four of the seven come straight out of the rules: the registered name, the disclosure set, the quote path, and the accurate use of the word broker. The verification route comes out of what the register cannot do. RIBO’s public searches take a broker’s name or a licence number, and nothing else — there is no way to ask which brokerages are in a given town. So the check a careful buyer wants to make only works if your site hands them both the name and the place to check it.
The order matters more than the count. The quote path depends on the disclosure set, so the disclosure set is the first thing built and every quote route reuses it. Everything after that is ordinary web design done carefully.
The name
“Websites must clearly identify the RIBO registered name of the brokerage. Websites cannot advertise or operate under a trade name only, as trade names are not legal entities.”
Advertising under any other name is misconduct in its own right: Reg. 991, s. 15 (1) 6. So is anything that leads a reasonable person to think a broker is an insurance agent: s. 15 (1) 10.
The moment
A quote is a “recommendation of one or more policies/coverages that includes price”. Disclosure is owed no later than then — and separately, at binding, in writing.
The guidance extends this to software: automated quoting “should include a process to provide mandatory disclosures at the point of quote”, drawn to the customer’s attention before documents go for signature.
The offer
No money or thing of value as an inducement to insure, and no rebate of premium: Reg. 991, s. 15 (1) 3, 4. Giveaways are allowed only if nominal — under $100 — and untied to a purchase.
Referral fees are restricted to a list of financial-services counterparts. Fees to non-financial parties are not permitted, which rules out a public refer-a-friend scheme.
| What a brokerage wants on the site | What the rules do with it |
|---|---|
| “We compare your policy against what you have now” | An incomplete comparison used to induce a lapse or surrender is misconduct. A page that teaches someone to read their own policy does the same job without a second column. |
| A wall of five-star reviews | Allowed, if nothing filtered them. Gating, incentivising, editing or fabricating them is misconduct — agency-run campaigns included. |
| “Get an instant quote online” | Allowed and expected to be fast: unjust delay in automated quoting is treated as declining coverage. The five disclosures must appear before the number. |
| “Switch and get a $50 gift card” | A thing of value offered as an inducement to insure. Not permitted, whatever it is called. |
| “Talk to one of our agents” | The wrong noun. Brokers and agents hold different licences and the regulation treats the confusion as misconduct. |
| A short trade name in the logo and nowhere else | The registered name has to be identifiable on the site. The trade name can stay; it just cannot stand alone. |
What does RIBO actually find when it inspects a brokerage?
Mostly paperwork, and the trend is worth knowing before you spend money on a website. RIBO completed 60 spot checks in 2024–2025. Written disclosure record keeping was compliant at 75%, where the year before 57% of brokerages did not have it. Take-All-Comers timing failures fell from 29% to 18%. Nine files, 15%, went to Investigations.
Read that against what RIBO’s renewal questionnaire says about the firms themselves. Over 900 firm licences renewed in the same year, alongside over 20,000 individual ones. Seventy-six per cent of firms sell auto insurance, so the Take-All-Comers rule — and the instantaneous-quoting expectation attached to it — applies to most of them. Twenty per cent have an insurer, bank, credit union or other company holding a direct or indirect ownership interest, which is the disclosure with no minimum threshold. And the average firm represents seven markets.
That last number is the one I would build a home page around. Seven markets is a real choice to describe, and describing it is how a visitor learns in the first screen that they are reading a brokerage rather than a captive agency.
Figures from RIBO’s 2024–2025 Spot Check Report and 2024–2025 Renewal Report. The renewal figures are self-reported by licensees at renewal, and RIBO publishes them as approximate.
What regulated-practice work have I done?
I have not built a site for an insurance brokerage, and I will say so on every page of this silo rather than once in small print. The closest build is a law firm in Richmond Hill, where a regulator also decides what the site may claim and the persuasion has to come from credentials rather than promises.
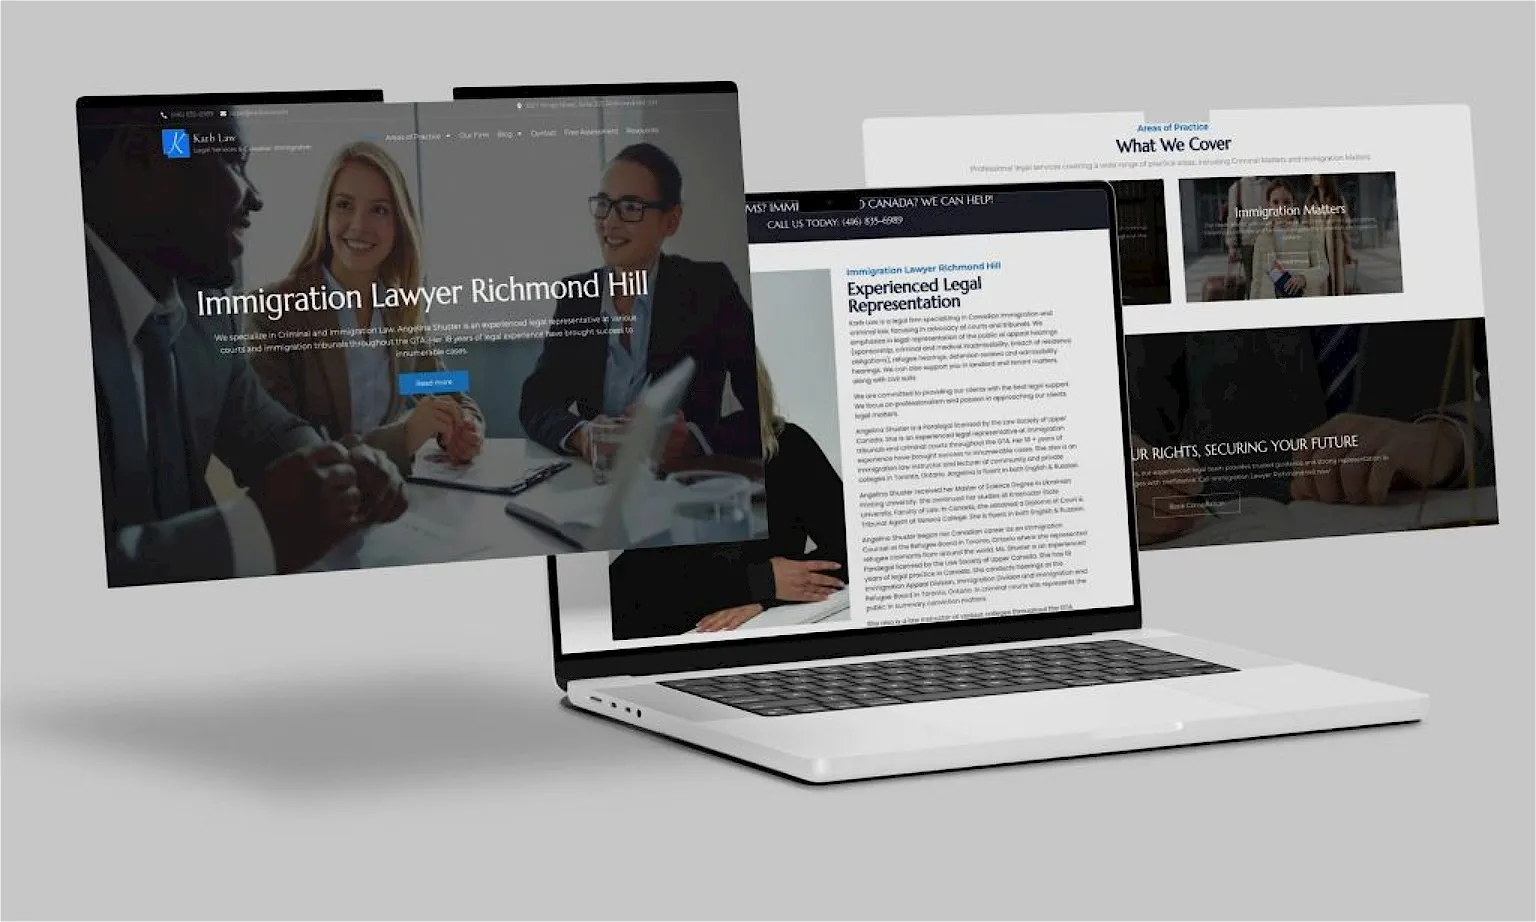
The regulated-practice build
Designed and built here, from an empty folder. Karb Law is a legal services firm in Richmond Hill, Ontario — mobile-first, hand-coded, structured for local search, no template and no page builder. The constraint that makes it relevant is the one an insurance brokerage lives with: a licensed title, a disclosure that has to arrive before the conversation does, and no outcome that may be promised.
The same build anchors the other regulated practices in this part of the site — mortgage brokers and agents and accounting firms and CPAs. On the insurance side, the public adjusting build covers the claims half of the industry. Read the law firm case study.
Insurance broker web design by city
Each city page is written from the market that is actually there — how many firms, how big they are, and who they are competing with for the same search.
Across Ontario, Statistics Canada counts 4,024 businesses with employees in the insurance agencies, brokerages and other insurance related activities group, spread over 254 census subdivisions; 74 of those municipalities have exactly one. That shape is why I write one honest local page per market rather than a page per town.
What does an insurance brokerage website cost?
A build of this scope is $899 to $2,999 one time and goes live in 5 to 7 days once content is ready. The variable that moves it most is how many lines of business need their own page and their own quote path, followed by whether an online quoter is embedded and has to carry the disclosures.
If you already have a site, the free website audit shows what a visitor cannot find on it, and on a brokerage site that first read doubles as a pass over the name, the disclosures and anything being offered. For the listing that appears beside the site when someone searches a line of business and a town, see Google Maps setup. The full breakdown is on the pricing page, and more about how I work is on the author page and about us.
Nothing here is legal or compliance advice. It is a reading of published rules by the person who would build the site; your principal broker signs off on what it says.
Common questions
What should an insurance brokerage website include?+
A home page carrying the registered name of the brokerage, a page for each line of business, a disclosure set covering compensation, third-party financial interest and sales incentives, a quote path that presents those disclosures before a price, a claims page written for an existing client, a people page that uses the word broker accurately, and a route to the RIBO brokerage search.
Does Ontario regulate what an insurance brokerage puts on its website?+
Yes. RIBO’s Guidelines on Marketing Practices carry a section headed Websites, and section 15 (1) of Regulation 991 makes advertising in any name other than the registered name, advertising that misrepresents by omission, and offering a thing of value as an inducement to insure acts of misconduct.
What are the five mandatory disclosures?+
Duty of care, meaning the CISRO Principles of Conduct and the Fact Sheet About Your Registered Insurance Broker; compensation and commissions including contingent profit commissions; any third-party financial interest, with no minimum threshold; sales incentives received for selling the policy; and anything else pertinent, such as an exclusive market or a referral fee.
Is review gating allowed for an insurance brokerage?+
No. RIBO Guidance RIBO-006, published on 1 June 2026, defines review gating as filtering reviews so that only positive ones are publicly visible, and treats it as a false and misleading form of advertising prohibited by section 15 (1) paragraph 1 of Regulation 991. Asking for reviews is still allowed.
How many insurance brokerages are there in Ontario?+
RIBO received over 20,000 individual renewals and over 900 firm renewals in the 2024 to 2025 licence year. Statistics Canada separately counts 4,024 businesses with employees in Ontario in the insurance agencies, brokerages and other insurance related activities group, spread across 254 census subdivisions.
How much does an insurance brokerage website cost?+
A build of this scope is $899 to $2,999 one time and goes live in 5 to 7 days once content is ready. The number of lines of business that need their own page and quote path is the variable that moves it most, followed by whether an online quoter is embedded.
Send me your markets list, and I will map the pages
Tell me which lines of business you write and which markets you represent — you get a page map back, with the disclosure set already placed, before any quote. Packages from $899.